

-
The Ritz-Carlton, Berlin
Join fellow attendees for an evening of drinks and networking ahead of the summit. Register in advance and start making valuable connections before the summit begins.
-
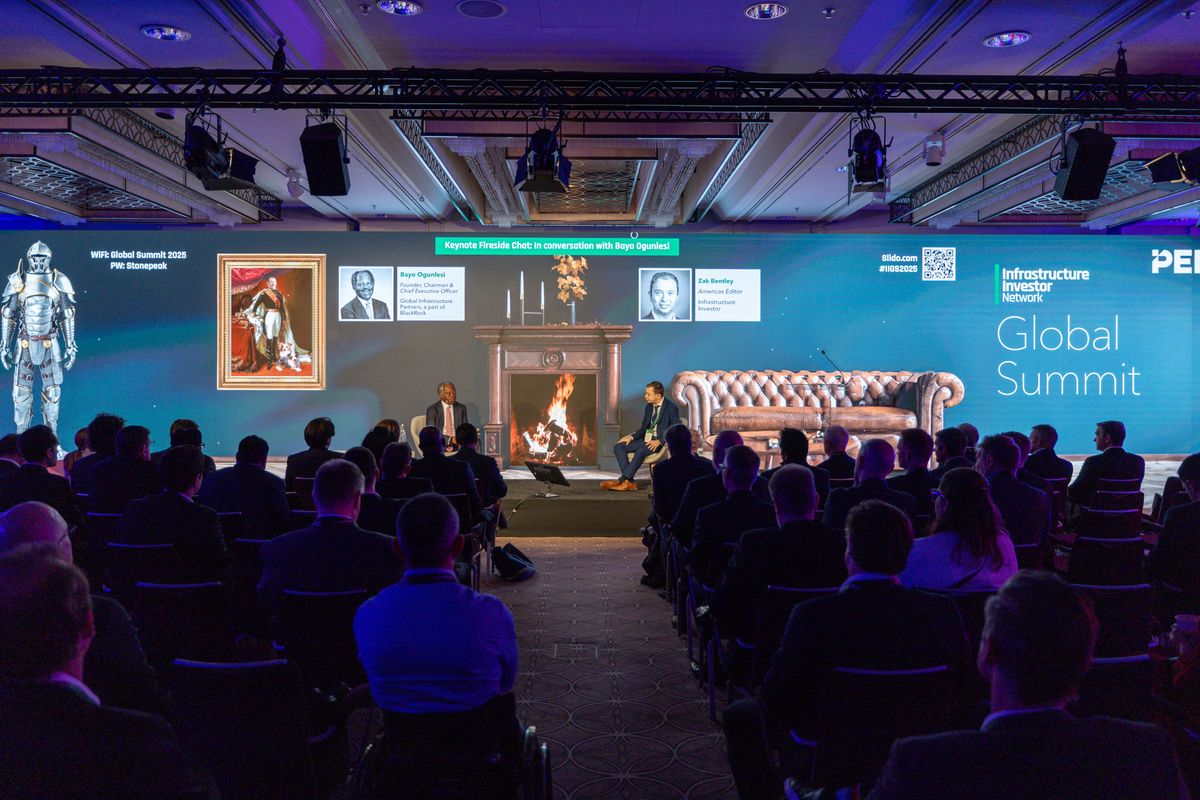
Featuring the editor of Infrastructure Investor alongside industry titans, this interactive session will take the pulse of the private infrastructure market - combining expert perspectives with real-time audience sentiment. How bullish is the market on returns? Where are the biggest risks over the next 12–24 months? And where are the most compelling risk-adjusted opportunities emerging? Cast your vote, benchmark your views against the room and join the debate.
-
- Dissecting the narrative shift in infrastructure amidst recent geopolitical volatility
- Compressing return expectations for LPs - re-pricing of risk or a permanent reset?
- Inflation linkage as a hedge – is this still a source of protection and is it reflected in valuations?
-
- Reframing the AI bubble question around long-term infrastructure – short-term hype
- Is the pace of spending and scale of AI capex sustainable, or a sign of bubble-like overcommitment?
- How can investors distinguish structural demand from temporary AI-driven capacity requirements?
-
- The scale of demand in the age of the AI power crunch
- Interconnection as the real bottleneck
- The causal link between rising wholesale prices and community fallout
- What does genuine modernisation of the grid require?
-
Structured, timed introductions across LPs, GPs and advisors to build the connections that carry through the rest of the summit.
-
- Is mid-market fundraising holding up on a deal-count basis?
- The expanding definition of transport, logistics & other sectors in the mid-market space
- Assessing the impact of megafunds encroaching on mid-market territory
Speakers
-
- How has the politics-infrastructure relationship evolved?
- Defence as Europe's pivotal new infrastructure theme?
- The role of PPPs in modern infrastructure investment - do they still hold up?
-
- From 'show me the opportunity' to 'show me the defensiveness' - evolving LP considerations
- Land, power and permitting as real supply constraints
- Tackling the community engagement problem
-
- The structural shift from bank lending to private debt funds
- Divergent regulatory timelines including Basel IV: EU, UK, US & elsewhere, and what that means for infrastructure credit
- Capturing the origination opportunity
-
- From training campuses to inference at the edge - breaking the old location rulebook?
- Where are the new frontiers showing up?
- The training/inference location split
-
- Strategic: long-term targets amid compressing returns
- Tactical: risk and valuation views in real time
- Operational: the co-investment/direct/fund debate - are we seeing a re-balancing?
- Concentration risk as an emerging governance concern
-
This hands-on workshop will take members through a realistic threat scenario to test how GPs and LPs assess cyber exposure in due diligence, what good governance and resilience planning look like across a portfolio, and where the biggest gaps tend to sit. Members will leave with a practical checklist for questions to ask of their assets and managers.
-
- Nvidia's $500bn+ compute financing partnership with leading infra managers
- Is compute a new infrastructure category in its own right?
- What does this mean for investors and other managers?
-
- The evolving opportunity set
- GP-led single/multi-asset vs. traditional LP deals
- The pricing squeeze on the LP-deal side
Speakers -
- Digging into the detail: distinguishing well-structured deals from speculative ones
- Hyperscaler capex hitting new highs
- The daisy-chain question: the trade-off between independent cashflow and circular financing
- Is there a real overbuild risk?
-
In this off-the-record, small-group workshop, GPs, LPs and advisers will work through how firms are planning succession, attracting and keeping operating talent, and keeping compensation and culture aligned as teams grow. Members will leave with practical frameworks and peer examples they can take straight back to their own organisations.
-
- The GP consolidation wave - impacts on the market
- To what extent is insurance capital reshaping ownership?
- Scale as a competitive necessity, not just a nice-to-have advantage
-
- Dissecting the blackout, cyber and interconnection challenge
- Data centers - resilience risk or resilience partner?
- Addressing the capital allocation challenge for resilience capex - proving the ROI case to investors

-
- Assessing the shortfalls with renewables returns and merchant price exposure
- Where have mistakes been made, and what lessons have been learnt?
- Redefining 'energy transition' - is power taking over as a thematic?
Speakers -
- Examining the macro backdrop - rates, valuations, AI-driven capital flows
- The role of private infrastructure leaders in a deglobalized world
- Where women are gaining ground in GP leadership, fund formation and LP allocation roles
-
- Live case studies from recent mid-market transactions across sectors and regions
- How are mid-market GPs are differentiating sourcing from megafunds moving downmarket?
- Operational value creation levers unique to mid-market platforms versus larger buyouts
-
- The premium being paid for data centers and the risks behind it
- Public market nervousness vs. operator conviction
- Construction cost inflation and replacement-cost economics
-
Small-group roundtable discussions building on the preceding panel, open to all delegates supporting greater diversity across the asset class.
-
- Large-cap vs. small/mid-cap performance thresholds
- The performance debate: outperformance or sector timing?
- Who's actually 'in' the mid-market and who isn't?

-
- To what extent is Infrastructure becoming a tool for national sovereignty?
- The sovereign AI compute build-out as the leading edge?
- Assessing risk in the sovereignty trade amidst geopolitical volatility
-
- Why critical minerals processing and border interconnectors are increasingly being treated as investable infrastructure in their own right
- Supply chain security concerns turning into a genuine private capital opportunity
- How are investors underwriting geopolitical risk in minerals and relevant supply chains?
-
- Considering tariffs and trade policy as a live variable
- The post-OBBBA renewables pivot
- Addressing the data center paradox: growth & opportunity vs political & local backlash
-
- Defining infrastructure-adjacent opportunities
- Long-term, contract-based - which characteristics are key?
- The classification challenge for LPs and GPs
- How far can the definition stretch before becoming strategy drift?
Speakers -
- Measuring skill-based performance data
- Direct alpha vs. traditional manager benchmarking
- Does GP outperformance persist across vintages, or is it noise?
- The LP view: how these findings shape manager selection and re-up decisions
-
- Germany: the €500bn defence-linked infrastructure opportunity
- UK: new leadership and the National Wealth Fund
- France: political dysfunction as a value opportunity
- CEE: from catching-up story to allocation destination
- Where else lies opportunity?
Speakers
-
- Are we experiencing a market correction on the impact and ESG agenda?
- Conservatism vs. conviction on renewables and ESG approaches
- Lessons for considering impact-driven allocations going forward
-
- Real fundraising and portfolio-construction case studies from recent first-time and second-fund managers
- What are LPs screening for when building emerging manager programmes?
- Overcoming hurdles to move forward from the emerging manager profile
-
- Refocusing the lens - from giga-cities to AI infrastructure & energy?
- Tracking the boots-on-the-ground GP build-out
- Considering conflicts and geopolitics in a volatile Gulf region
-
- Lessons learned from UK and other regional water utility issues
- Reframing water as a growth opportunity
- Industrial demand as an underappreciated driver - how to seize the advantage
-
Small-group roundtables building on the preceding case studies, for first-time and emerging fund managers to connect with LPs actively building emerging manager programmes.
-
- The LP starting point: Australia over-allocated, other regions under-allocated?
- The fund-vs-direct pivot reshaping Australian LP behaviour - how does this compare to LP capital allocation across Asia?
- Where capital is being committed, and in which sectors?
-
- Making the infrastructure case for waste and materials
- Where is circular economy capital flowing? How do different organisations approach it?
- Logistics’ identity crisis - real estate or infrastructure, and why it matters
-
- The J-curve, downside protection and the narrowing debt/equity spread - where do specific strategies land?
- Secondaries - the natural non-primary route and a growth market?
- Building a balanced portfolio across primaries, secondaries, credit and CVs
-
- A glance at the scoreboard - how investment and spend between clean and traditional energy compares globally
- The real rebalancing story: grids and battery storage focus over renewables vs fossil fuel?
- Demand opening the door - natural gas's AI-driven moment?
Jerry Divoky, Senior Managing Director, BCI
Christine Martmann, Managing Director, CPPIB
-
Robert Habeck, Professor in Practise at Copenhagen Business School, writer and former politician
in conversation with
-
- Rolling stock, rail services, ports and regional airports: mature, contracted transport assets below the megafund radar
- Minority and co-control stakes: partnering with strategic and co-owners without paying a control premium
- Who buys next? Exit routes for European transport assets in 2027
-
- Operational value creation as the dominant return driver
- GPs building direct development capability in-house
- Is the GP/LP division of labour collapsing?
Speakers -
- SIPA's latest performance and benchmarking data
- What does the data mean for LP and GP decision-making?
- Equity and debt performance, sector and regional benchmarks, and manager alpha
-
- Considering the full spectrum: stratospheric managers, squeezed mid-market, zombie managers
- What's driving top-heavy concentration?
- The GP relevance question
-
Small-group roundtable discussions building on the preceding panel, exploring how LPs and GPs are navigating the shift toward direct operational ownership.
-
Defining the broad range of infrastructure credit strategies
Performance, defaults and recovery rates across the risk spectrum
Benchmarking GP/manager selection in credit
-
- Detailing the scale of the shift into infrastructure allocations
- Partnerships with fund managers
- Going direct, going bigger and betting on AI infrastructure
-
- Live case studies from recent deals across MENA, APAC, Latin America and CEE
- What separates a bankable growth-market transaction from one that stalls at financial close?
- How GPs are structuring risk mitigation in practice
-
- Big Tech's involvement & AI data center demand
- Tracking the numbers - how is deal volume ramping up?
- Is this genuine core infrastructure yet, or still venture/technology risk in an infrastructure wrapper?
-
- DPI - the metric that matters most to LPs?
- The scale of the distributions drought
- The toolkit for crystallising DPI: CVs, partial exits, dividend recaps
-
Small-group roundtables building on the preceding case studies, for LPs and GPs active across MENA, APAC, Latin America and CEE to connect on cross-border deal flow and co-investment.
-
- The shift toward quality over quantity: de-risked, operational projects over greenfield development
- The AI/data center connection: on-site storage expanding into grid services
- Considering technology risk and durability around lithium-ion and elsewhere
-
- How do platform-seeded vehicles compare with traditional blind-pool fundraising?
- Continuation vehicles, evergreens and thematic strategies converging on the same platforms - raising questions of conflicts of interest, valuation consistency and governance
- Who does platform power truly work for in the market?
-
- The scale of evergreen and semi-liquid fund flows
- Have recent private credit stress & redemptions strengthened infrastructure’s appeal for private wealth?
- Facing the liquidity question for retail investors in an illiquid asset class
-
- Why transport has lagged behind digital and energy in LP portfolios, and is this slowly changing?
- The access problem: specialist vs. generalist managers
- How are flexible allocators solving the access disconnect?
Speakers
-
- Addressing the persistent bid-ask spread standoff
- Is asset-size growth shrinking the buyer pool?
- What impact does this have on exits and LP concerns?
-
Wealth managers, private banks and evergreen/ELTIF product teams connect with GPs building out private wealth distribution.
-
- Assessing the sheer scale of trade disruption hitting hard infrastructure
- How is geopolitics physically rerouting global shipping? And what impact does that have on investors?
- Unique challenges and opportunities in the aviation market
- Where can disciplined GPs and LPs find value?
-
- Sizing the opportunity - how much capital is being launched into space?
- What exactly GPs are underwriting: ground stations, broadband, Earth observation data and beyond
- What should LPs be asking as satellites are classified critical infrastructure?
-
- A record 2025 vs a slow 2026 - what’s the outlier and where are we now?
- Why is it taking longer for funds to achieve final close?
- The LP allocation gap: conviction vs distribution
- Flight to quality - where allocations are actually landing
-
- The latest PEI fundraising data: totals, time-to-close, and manager concentration
- How 2025's record haul compares with a slower 2026, and what 2027 might have in store
- Where the push for quality is showing up most clearly in the numbers
-
- The portfolio-construction case: return expectations versus equities, PE, real estate, direct lending and bonds
- Championing the long-term play? How has infrastructure stacked up to geopolitical volatility?
- Infrastructure's maturing toolkit - secondaries, CVs, evergreens - versus its closest private-market peers
- Does infrastructure’s future belong outside of the alternatives bucket?
-
- Is the 'emerging market' label itself outdated?
- Diverging return drivers by market type
- The bankability gap in practice
- How are global GPs and LPs now approaching increasingly intertwined markets?
-
- Where is the convergence most visible?
- Assets that look like real estate but behave like infrastructure economically
- The benefits case: enhance risk/return vs siloed approach?
- The cons: does bucketing them together risk masking different risk drivers?
-
- Where AI is saving time: origination, diligence, LP reporting and more
- What do LPs now expect from their GPs regarding AI application?
- Does AI adoption widen the gap between leading and lagging managers?